




Prospects for the U.S. EconomySpeech at the Golden Gate University Speakers SeriesSan Francisco, California By Janet L. Yellen, President and CEO of the Federal Reserve Bank of San FranciscoFor delivery July 31, 2006 – 8:45 AM Pacific Daylight Time, 11:45 AM EasternProspects for the U.S. EconomyThank you very much for inviting me to join you. It's a real pleasure to be part of this outstanding speakers series. Today I will discuss my views on the prospects for the U.S. economy—for labor markets and economic activity and also for inflation. This focus mirrors the two main objectives for monetary policy enunciated in the Federal Reserve Act, namely maximum employment and price stability. I plan to explore the implications of these developments for monetary policy. Then, of course, I would welcome your questions and comments. Before I begin, let me note that my remarks represent my own views and are not necessarily those of my colleagues in the Federal Reserve System.The U.S. economy has shown remarkable resilience in the face of some severe shocks—in particular, the surge in energy prices that began a couple of years ago and the devastation from the twin hurricanes last summer. Over the past two years, economic growth has averaged just over 31/4 percent, moderately above current estimates of the growth rate that is sustainable in the long run. As a result, the economy now appears to have moved within range of the full utilization of its resources—in other words, the slack in labor and product markets that was apparent a year ago has most likely been eliminated. For example, over that time, both the rate of unused capacity in the industrial sector and the civilian unemployment rate have fallen noticeably.Indeed, the unemployment rate dropped by one full percentage point, coming in at just over 4½ percent in June. This rate is actually a bit lower than conventional estimates of so-called "full employment," and therefore suggests that there may be a bit of excess demand in labor markets.However, the benchmark for these calculations—full employment or utilization—cannot be measured with a lot of precision, and may change over time. As a check on the degree of utilization, I like to look at the behavior of labor compensation, including both wages and benefits. If, for example, labor markets were excessively tight, it seems likely that we would see a pickup in the growth of labor compensation as firms competed for scarce workers. Instead, based on the most recent data, we find that broad measures of compensation increased at a moderate rate over the past year. Nonetheless, tight labor markets could affect labor compensation with a lag, so it's possible that there is pressure for acceleration in the pipeline. Moreover, these broad measures may have been held down by a deceleration in benefits costs—for example, there has been a sharp slowdown in the growth of health insurance costs—which may have only a temporary effect on overall compensation. So, while moderate growth in compensation provides me with some degree of comfort that we have not overshot full utilization, or, at least, not by very much, the jury is still out on this issue.With labor and product markets close to full utilization, the key concern going forward is whether economic growth will slow enough and for long enough to avoid a buildup of inflationary pressures. Recent data indicate that real GDP growth did slow noticeably in the second quarter, coming in at 2½ percent. This is well below the rapid 5½ rate in the first quarter, and moderately below most estimates of the rate that is sustainable in the long run.My best guess is that growth will still be healthy but will remain somewhat below the sustainable rate as the year progresses. This outlook represents the net effect of a number of disparate forces. The impetus to keep the economy ticking along includes factors such as ongoing strength in the fundamentals for productivity and relatively rapid growth in business investment in equipment and software—including the vital high-tech sector—as well as in spending on nonresidential structures.As for the factors that are likely to restrain growth, there is the rise in both short- and long-term interest rates over the past couple of years as the Fed has removed monetary policy accommodation. Since mid-2004 when the Fed began this process, most short-term interest rates have increased between 3½ and 4 percentage points. Many long-term rates are up by ¼ to ½ of a percentage point, with most of this increase occurring since early this year. These higher rates should reduce demand, particularly in interest-sensitive sectors, notably, autos, consumer durables, and housing.Indeed, we have already seen some cooling in the housing sector, and this brings me to another factor that is likely to restrain growth—that is, the significant moderation in the rate of house-price appreciation. Slower increases in house prices could put a crimp in consumer spending in a couple of ways. First, some observers believe that consumers have been keeping their spending up by withdrawing equity from the increased value of their homes; of course, this source of funds starts to shrink as the pace of appreciation slows. Furthermore, there may be some pullback by consumers due what is called the wealth effect—that is, slower house-price appreciation reduces growth in their wealth and therefore their tendency to increase their spending.While I expect the housing situation to have only moderating effects on economic activity going forward, I should note that we can't ignore the risks of more unpleasant scenarios developing. One scenario that we have heard a lot about in recent years is the possibility that there is a house-price "bubble," implying that prices got out of line with the fundamental value of houses and that the current softening could be just the beginning of a more precipitous fall. While I seriously doubt that we'll see anything like a "popping of the bubble"—in part because I'm not convinced there is a bubble, at least on a national level—I certainly do acknowledge that there is more reason to worry that house prices would fall sharply than that they would rise sharply.A second scenario has to do with the wealth effect I mentioned and its impact on household saving behavior. In the U.S., the personal saving rate has been declining for years, and in the second quarter it reached minus 1½ percent. Part of this development probably relates to the growth in consumers' wealth in housing. As it has become easier and easier to tap into that wealth, people have felt less of a need to save from current income. But with the softening in house prices acting to slow consumers' accumulation of wealth, the urge to save rather than spend may resurge. In fact, consumer wealth is getting another hit from the recent declines in the stock market, which also may induce people to build up savings. So, the very low—in fact, negative—saving rate makes the chance of a sizeable drop-off in consumer spending seem larger than the chance of a big surge.Since housing is so important for the outlook, I'll spend a moment sketching in the overall picture for this sector. So far, the signs of cooling, including the deceleration in house-price appreciation, are broadly consistent with the degree of moderation I've envisioned, and fortunately these developments seem to be unfolding in an orderly way. After adjusting for inflation, residential investment has dropped by a total of 2 percent over the past three quarters. Housing permits are down from highs established earlier this year. In addition, inventories of unsold houses are up significantly, sales of new and existing homes are off their peaks, and surveys of home buyers and builders are showing more pessimistic attitudes. Finally, after long being stagnant, rents are finally moving up more vigorously. This may reflect, in part, expectations of lower house-price appreciation, as landlords raise rents to try to maintain the total rate of return on rental properties and as those in the market for housing grow more inclined to rent than to buy.Of course, housing markets are a big issue in the Bay Area, and we have seen the same kind of cooling as in the nation. The question of whether the housing stock here is overvalued and therefore particularly vulnerable to downside risk, however, is one I can't answer with any certainty. I would note that there are some special things about the Bay Area on both sides of the question. For example, consider some tentative evidence on the side of greater vulnerability. First, average house prices in the Bay Area are now about six times what they were in 1982, versus only 3½ times in the U.S. as a whole. Moreover, the ratio of house prices to rental rates—a measure of the price of houses relative to the flow of housing services they provide—has more than doubled since 1982, far out-stripping the national average. Even so, there are well-known and unique features of this area that lend some justification to its high housing values. First, there is not much land available for new home building, so the supply of new homes is fairly limited. In addition, this area enjoys very favorable lifestyle amenities and it has a job base that attracts high-income residents.In closing my description of the forecast for economic activity, I have to mention the big "wild card"—energy prices. And I'll return it to it when I discuss the inflation outlook. It is quite likely that rising energy prices have restrained consumer spending moderately even though offsets from job gains and wealth have kept it rising overall. If energy prices stabilize around their current levels, as futures markets indicate is expected, then the negative effect of energy on spending should dissipate over 2007. While we all certainly hope the energy futures markets are right, to be honest, their record hasn't been so great. During the whole period of rising energy prices that began in 2004, futures markets have usually predicted that the path of prices would be relatively flat, and they've had to revise the path up as energy prices have continued to exceed expectations. Basically, over this period, energy markets have been marked by strong demand, including demand from emerging markets—notably China—and by reportedly limited capacity to expand production. In addition, of course, there have been extraordinary events that threaten to restrict supply and therefore jack up energy prices, like the current situation in Lebanon and Israel. Needless to say, then, future energy prices are a big question mark, and any sustained rise or fall in these prices could either depress or spur economic activity beyond my current expectations.InflationThis brings me to the inflation part of the picture. The recent news has been disappointing. The measure of core consumer inflation that the FOMC projects for Congress—the personal consumption expenditures price index excluding the volatile food and energy components—has risen rather sharply in recent months. It rose by nearly 3 percent in the second quarter, which implies an increase over the past year of 2¼ percent. This rate is somewhat above my "comfort zone"—a range between one and two percent that I consider an appropriate long-run inflation objective for the Fed.Therefore, it is critical that core inflation trend in a downward direction over the medium term, and I think this is the most likely outcome. As I've said, I expect that the economy has entered a period of slightly below-trend growth that should relieve any underlying inflationary pressures emanating from tightness in labor and product markets. In addition, there are three other underlying factors that tend to bode well for future inflation. One I've already mentioned—labor compensation has been rising at a moderate rate. While there may be increases in the pipeline for the reasons I spelled out earlier, we haven't seen convincing signs of them so far. Second, productivity growth has remained strong, maintaining the pattern of strength established in the latter half of the 1990s. Finally, markups by businesses of product prices over costs are at historic highs. So, even if costs begin to rise, firms would have the room to absorb the increases without raising their prices.Next, there is the issue of the role of energy prices in the recent disappointing data on core inflation. As I said, core inflation excludes energy prices. But there may have been some passthrough of higher energy prices into the prices of core goods that use energy as an input to production—airfares are a good example. If this is the case, and if energy prices level out as expected by futures markets, this pressure is likely to dissipate at some point. However, the whole question of passthrough is actually the subject of some debate. For example, recent evidence suggests that there has been much less passthrough in the past twenty-five years than there was back in the 1970s, when inflation got out of control in the face of soaring energy prices. If it's true that there's only a very small passthrough of higher energy prices to inflation currently, then that raises the concern that something more fundamental is pushing up inflation. Unfortunately, at this point, it's too soon to untangle these alternative interpretations.Finally, inflation expectations must be considered in any discussion of inflation. No matter what the cause of the recent increases in core inflation, it is important that they do not get built into longer-term inflation expectations and, in turn, wages. Research suggests that expectations have been well-anchored to price stability in recent years because people have confidence that the Fed will act to limit any sustained rise in inflation. This result shows up in the stability of survey and market measures of inflation expectations in the face of the large energy price increases we've seen. But, I want to emphasize that this is not something that I—or my colleagues—take for granted. Maintaining credibility requires that we act when necessary to keep inflation under control.I've explained why I think there are reasons to expect inflation to move gradually lower in the future. However, I am keenly aware that this pattern has yet to show up in the data. And, given the inherent uncertainties, I would say that there are currently upside risks to this inflation forecast.Policy issuesThis leads me to the concluding topic in my presentation today—the implications of recent economic developments for monetary policy. With inflation now too high and labor and product markets in the vicinity of full utilization—or perhaps even a bit beyond it—a period of growth modestly below trend would ease any cyclical pressures on core inflation and, given the other elements in the inflation outlook that I just discussed, would be likely to set the stage for a gradual decline back into my comfort zone.In these circumstances, it might be thought that policy should continue to tighten until the inflation data move back to a rate consistent with price stability. But I would argue that a gradual approach is likely to be better. Let me illustrate this point with a medical analogy. Suppose you go to the doctor for your annual physical and she finds you have high blood pressure—say, 150 over 100. The doctor prescribes medication to get it down toward 120 over 80. She tells you that the evidence indicates that it takes a while for the medication to work, so you should take one pill a day for a week and then retest your blood pressure. You take the pill the first day. On the second day, you're worried and nervous—elevated blood pressure is no laughing matter—and you can't resist taking another reading. When you do, you find that your pressure is still up there. You are so worried about the ill effects of your condition that you figure that it's okay to take two pills instead of the one the doctor prescribed. You repeat this pattern on the third day, as well, upping the dosage to three pills. This approach almost certainly will reduce your blood pressure. But by not properly considering the lags between the time you take the medicine and the time it takes effect, you could end up with blood pressure that's too low, and that could well present its own health hazards.The need to incorporate lags between policy actions and effects on the economy is a key issue for monetary policy as well. We don't know what the lags are with precision, but we still need to do the best we can to take them into account. We simply don't get the necessary feedback on the effects of our policy actions for a long time. So if we kept automatically raising rates until we saw inflation start to respond, we most likely would have gone too far. Instead we need to be forward-looking.That is why I've focused today on the economic outlook, and particularly on those aspects of the outlook that pertain to the dual mandate the Congress has given the Fed. We are charged with achieving both price stability and maximum sustainable employment. So, for all of these reasons, it makes sense for us to target a forecast for inflation, output, and employment—in other words, to set the funds rate at a level that is likely to foster a desirable path for the economy.However, forecasts are uncertain and depend heavily on the particular view of the world—or model—that is being used. That's why I also like to use other methods to obtain benchmarks for the thrust of our policies in the future. One alternative approach is to estimate the so-called neutral federal funds rate, which is defined as the rate—or policy setting—that would be consistent in the intermediate run with stable inflation and full employment. If we could determine what the neutral rate is, we could set the actual rate appropriately. For example, in the present circumstances, I would consider it appropriate for the actual rate to be a bit above the neutral rate—in other words, I'd like it to be modestly restrictive—to promote price stability, especially given that the economy may be operating with labor and product markets that are a bit on the tight side. Estimates of the neutral rate can be based on a variety of large and small models and on statistical techniques. Of course, we can't get precise estimates, only an indication that can be helpful along with other benchmarks.Another approach involves monetary policy rules—such as the so-called Taylor rule—that can be consulted for appropriate policy settings. These rules incorporate estimates of the neutral federal funds rate as a benchmark. They then prescribe how the actual funds rate should stand relative to the neutral rate depending on how inflation and resource utilization stand relative to our dual mandates—price stability and full utilization. So, for example, if inflation is above a particular definition of price stability, the rules will say that the funds rate should be above the neutral rate. These rules have been shown to broadly characterize actual Fed monetary policies that have been successful in the past.Consulting all of these approaches, it appears to me that the federal funds rate currently lies in a vicinity that is roughly appropriate for the Fed to attain its key objectives over the medium run. However, since all such approaches are inherently imprecise, policy must be responsive to the data that actually emerges. When I say that policy should be responsive to the data, I mean that the extent and timing of any additional firming should depend on how emerging developments affect the economic outlook. And when I say data, I don't just mean data on inflation, output, and employment. I also mean data on factors that might affect those variables in the future—such as energy prices, the dollar, the stock market, long-term interest rates, housing prices and inflation expectations.I believe that the wording of the policy statement the FOMC issued at the end of June—following our last meeting—succinctly captures the essence of the basic point I'm making: it states that "Although the moderation in the growth of aggregate demand should help to limit inflation pressures over time, the Committee judges that some inflation risks remain. The extent and timing of any additional firming that may be needed to address these risks will depend on the evolution of the outlook for both inflation and economic growth, as implied by incoming information."Thank you for having me today, and I will be pleased to address your questions.

[관련키워드]


[뉴스핌 베스트 기사]
 사진
프로야구 삼성, 12년 만에 한국시리즈 우승
*AI를 활용해 정리한 경기 내용입니다. 상단의 'AI MY 뉴스' 로그인을 통해 뉴스핌의 차세대 AI 콘텐츠 서비스를 활용해보기 바랍니다.
[서울=뉴스핌] 유다연 기자=12년의 기다림이 끝났다. 삼성이 정규시즌 1위 KT 위즈를 꺾고 2014년 이후 12년 만에 한국시리즈(KS·7전 4선승제) 정상에 복귀했다.
삼성은 8일 대구삼성라이온즈파크에서 열린 KT와의 2026 KBO KS 5차전에서 12-1로 대승을 거뒀다.
[서울=뉴스핌] 유다연 기자= 삼성 라이온즈가 8일 대구 삼성라이온즈파크에서 열린 2026 KBO 한국시리즈 5차전에서 12-1로 이겼다. 이날 우승으로 삼성은 12년 만에 KS 정상자리에 올랐다. 그래픽은 독자의 이해를 돕기 위해 삼성 선수들 사진과 함께 만든 AI그래픽. (명령어: 삼성 라이온즈 12년 만의 우승을 AI그래픽으로 제작해줘.)[사진=삼성 라이온즈][그래픽=챗 GPT] 2026.11.08 willowdy@newspim.com
지난 3일 수원에서 열린 1차전에서 7-8로 패했던 삼성은 2차전 연장 12회 혈투 끝에 승리하며 시리즈 균형을 맞췄다. 이후 안방에서 열린 3~5차전을 모두 쓸어 담으며 시리즈 전적 4승 1패로 우승을 확정했다. 이로써 삼성은 2002년, 2005년, 2006년, 2011~2014년에 이어 통산 8번째 KS 우승을 차지했다. 1985년 전·후기 통합우승까지 포함하면 구단 통산 9번째 우승이다.
특히 정규시즌 2위였던 삼성은 1위 KT를 제압하면서 2018년 SK(현 SSG) 이후 8년 만에 '업셋 우승'을 달성했다. 반면 KT는 2021년 창단 첫 통합우승 이후 5년 만에 두 번째 통합우승을 노렸으나 삼성의 기세를 넘지 못했다.
삼성의 주장 구자욱은 KS 최우수선수(MVP)에 선정되며 우승의 기쁨을 더했다.
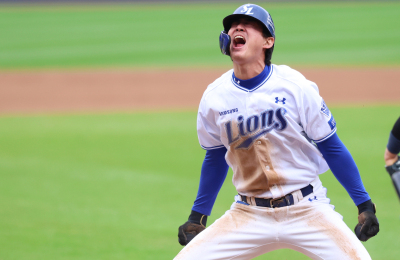
[서울=뉴스핌] 삼성 구자욱이 8일 대구 삼성 라이온즈파크에서 열린 KT와 2026 KBO 한국시리즈 5차전 득점을 기록해 포효하고 있다. [사진=삼성 라이온즈] 2026.11.08 willowdy@newspim.com
이날 선취점은 KT의 몫이었다. KT는 2회초 1사 1, 2루 기회를 놓쳤지만 3회초 선제점을 뽑아냈다. 선두타자 한승택이 유격수를 맞고 외야로 빠져나가는 안타로 출루했고, 권동진의 좌중간 안타와 최원준의 희생번트를 묶어 1사 2, 3루 기회를 잡았다. 이어 장진혁이 중견수 희생플라이를 날려 1-0으로 앞서갔다.
하지만 삼성은 곧바로 승부를 뒤집었다. 3회말 1사 후 김지찬이 스트레이트 볼넷으로 출루했다. 2사 후 타석에 들어선 구자욱이 우익선상 1타점 2루타를 터뜨리며 1-1 동점을 만들었다.
이어 르윈 디아즈가 오른쪽 담장을 직격하는 1타점 적시타를 날려 2-1로 역전했다. 계속된 공격에서 최형우의 우전 안타로 기회를 이어간 삼성은 김영웅의 좌중간 적시타까지 터지면서 3-1로 달아났다. 디아즈의 적시타는 이날 결승타가 됐다.
KT는 4회초 1사 2루, 5회초 1사 1, 2루 기회를 잡았지만 후속타 불발로 추격에 실패했다. 위기를 넘긴 삼성은 5회말 타선이 폭발하며 사실상 승부를 결정지었다.
삼성은 5회말 박승규가 상대 유격수의 포구 실책으로 출루하며 공격의 물꼬를 텄다. 이후 구자욱의 우전 안타로 1사 1, 2루 기회를 잡았다. 디아즈가 3루수 뜬공으로 물러났지만 최형우가 우익선상 1타점 적시타를 날리며 4-1로 달아났다. 이어 김영웅의 타구가 상대 2루수의 몸을 맞고 굴절되면서 내야안타가 됐고, 2루 주자 구자욱이 홈을 밟아 5-1을 만들었다.
[서울=뉴스핌] 삼성 강민호가 8일 대구 삼성라이온즈파크에서 열린 KT와 2026 KBO KS 5차전에서 적시타를 기록 후 환호하고 있다. [사진=삼성 라이온즈] 2026.11.08 willowdy@newspim.com
삼성의 공세는 멈추지 않았다. 이재현이 좌익선상 1타점 2루타를 터뜨리며 점수 차를 5점으로 벌렸다. KT는 류지혁을 자동 고의4구로 내보내며 만루 작전을 선택했다.
그러나 수비 실책이 뼈아팠다. 강민호가 2루수 앞으로 병살타성 땅볼을 쳤지만 KT의 2루수와 유격수 사이에서 송구와 포구가 제대로 이뤄지지 않았다. 그 사이 주자 2명이 홈을 밟으며 점수는 8-1까지 벌어졌다.
기세가 오른 삼성은 계속된 1, 3루에서 김지찬이 우중간을 가르는 2타점 3루타를 터뜨려 두 자릿수 득점을 완성했다. 이어 상대 투수 손동현의 폭투로 1점을 추가했다. 삼성은 5회말에만 8점을 몰아치며 11-1로 달아났다. 반면 KT는 연이은 수비 실책과 마운드 붕괴로 추격 동력을 잃었다.
삼성은 8회말에도 추가점을 뽑았다. 박승규의 투수 오른쪽 내야안타와 구자욱의 중전 안타로 만든 1사 1, 3루에서 김영웅의 타구가 유격수 권동진의 몸을 맞고 외야로 빠져나가면서 12-1을 만들었다. 이 과정에서 타구에 맞은 권동진은 구급차로 이송됐다.
마운드에서는 선발 원태인과 크리스 페덱이 KT 타선을 1점으로 묶으며 우승을 합작했다.
[서울=뉴스핌] 삼성 원태인과 강민호가 8일 대구 삼성 라이온즈파크에서 열린 2026 KBO KS 5차전에서 마운드를 내려오며 대화하고 있다. [사진=삼성 라이온즈] 2026.11.08 willowdy@newspim.com
원태인은 5이닝 동안 4피안타 2사사구 5탈삼진 1실점을 기록하며 승리투수가 됐다. 3회 선취점을 허용했지만 추가 실점 없이 5회까지 마운드를 지키며 팀의 역전승에 발판을 마련했다.
삼성은 6회부터 선발 자원인 페덱을 투입하며 굳히기에 나섰다. 페덱은 4이닝 동안 안타와 사사구를 단 한 개도 허용하지 않는 퍼펙트 투구를 펼쳤다. 탈삼진 4개를 곁들이며 KT의 반격을 원천 봉쇄하고 우승을 확정했다.
반면 KT 선발 데이비스 대니엘은 3이닝 5피안타 2사사구 4탈삼진 3실점으로 패전투수가 됐다. 뒤이어 등판한 고영표도 1.1이닝 5피안타 1사사구 1탈삼진 8실점(2자책점)으로 무너지면서 팀의 패배를 막지 못했다.
정규시즌 1위로 KS에 직행했던 KT는 1차전 승리 이후 4연패를 당하며 안방에서 우승 트로피를 들어 올리겠다는 목표를 이루지 못했다.
반면 정규시즌 2위로 플레이오프부터 가을야구를 시작한 삼성은 KIA를 꺾고 KS에 진출한 데 이어 KT까지 제압했다. 12년 만에 다시 정상에 오른 삼성은 대구 홈팬들 앞에서 통산 9번째 우승의 기쁨을 만끽했다.
*위 내용은 생성형 AI로 작성한 경기 상보 [명령어 : 11월 8일 대구 KT-삼성 KS 5차전 경기 내용을 정리해줘=CHAT GPT]
willowdy@newspim.com
2026-11-08 17:21
 사진
엔비디아 '젠슨 황 장녀' 방한 돌연 취소?
[서울=뉴스핌] 백승은 기자 = 젠슨 황 엔비디아 최고경영자(CEO)의 장녀 매디슨 황 엔비디아 수석이사가 한국 방문 계획을 돌연 취소했다.
9일 IT업계에 따르면 매디슨 황 엔비디아 옴니버스·로보틱스 제품 마케팅 수석이사는 방한 일정을 취소했다. 단 구체적인 사유는 공개되지 않았다.
지난 8월 LG 데이터팩토리를 방문한 매디슨 황 엔비디아 수석이사 [사진=뉴스핌DB]
이번 방한은 9~10일 열리는 '엔비디아 AI 데이 서울 2026' 행사에 참석하기 위함이었다. 그렇지만 방한 일정이 취소되며 배경훈 부총리 겸 과학기술정보통신부 장관과의 면담 등 국내 주요 일정이 모두 무산됐다.
단 행사는 예정대로 진행된다. 국내 기업 협력 행사에는 엔비디아의 다른 임원이 대신 참석할 예정이다.
업계에서는 젠슨 황 CEO 주변 인물의 '중국 스파이' 연루 의혹이 방한 취소에 영향을 미친 게 아니냐는 관측이 제기된다.
100wins@newspim.com
2026-11-08 11:39











