美 연준 정책결정가들은 지난 9월 20일 회의에서 허리케인 카트리나가 이러한 충격 이전부터 "이미 상당한 수준에 도달했던" 인플레이션 압력을 크게 상승시켰다고 판단, 추가 금리인상이 필요하다는 결론을 내린 사실이 확인됐다.지난 FOMC는 연방기금 금리를 3.5%에서 3.75%로 인상하기로 결정했으나, 이 수준은 "인플레이션 압력을 억제하기에 필요한 수준보다 낮은 것이며, 추가적인 금리인상이 요구될 것"이라고 평가했다고 11일(美 현지시간) 발표된 9월 의사록은 쓰고 있다.이번 의사록은 한편 연준이 성명서 기조를 금리인상 전망을 좀 덜 시사하는 방향으로 조만간 변경할 가능성도 높이고 있다. 의사록에서 연준 관계자들은 "다음 회의부터는 성명서에 포함된 향후 정책방향과 관련된 문구를 변경" 하는 것이 "다소 합당할 것"이라고 지적했다. 이는 부분적으로는 연준이 그 동안 완화적 기조를 어느 정도까지는 제거했다는 점도 반영한 것이다. 그 동안 연준은 자신들의 금리인상에도 불구하고 기준금리가 계속 중립수준보다 낮은 상태에 있다고 말해왔다.결국 이런 점들을 고려한다면 연준 정책결정자들은 이제 금리의 중립수준 회복을 넘서 보다 명백한 억제 정책을 구사하는 방향으로 넘어가고 있다는 느낌을 주고 있는 셈이다.지난 9월 금리인상 결정은 그러나 2003년 6월 이후 처음으로 투표권을 가진 멤버로부터 한 표의 반대가 나왔다. 반대표를 던진 마크 올슨 이사는 카트리나 충격 이후 거시지표 결과를 좀 더 지켜보자는 입장에서 그렇게 한 것으로 확인됐다. 그러나 나머지 정책결정가들은 이러한 올슨 이사의 견해를 공유하지 않았다.이들은 비록 허리케인이 불확실성을 증대시켰다는 점을 인정하면서도 "장기적인 경제 전망을 결정하는 펀더멘털한 요소들은 거의 영향을 받지 않았으며, 오히려 인플레이션 리스크가 증가한 것으로 보인다(the longer-term path of the economy probably had not been affected by the hurricane, but the upside risks to inflation appeared to have increased)"는 평가를 내렸다고 의사록은 적고 있다.금융시장 참가자들은 이러한 강경한 입장은 연준이 11월 초 회의에서 금리를 4%로 인상하는 것은 물론 2006년 중반까지 금리를 4.50%선까지 추가 인상할 것임을 시사하는 것으로 받아들이고 있다.이번 회의에서 연준 스탭들은 2005년 경제성장률 전망치를 하향조정하였으나 2006년 전망치는 상향조정했는데, 이는 "재해복구를 위한 경제적 활동이 지니는 부양요인을 반영한 것"이라고 지적됐다. 연준 스탭들은 2007년까지 美 경제가 허리케인 영향을 받지 않은 이전 수준으로 회복될 것이라고 주장했다.한편 이들은 인플레이션 압력에 대해서는 2005년 전망치를 상향조정하고, 2006년에도 코어 인플레이션 압력이 "높은 에너지 물가 영향을 반영할 것"이라고 전망했다. 그러나 연준의 2006년 전체 인플레이션 전망치는 다소 하향수정되었다.이번 의사록을 보면 지난 9월 FOMC회의는 많은 부분 인플레이션 압력에 대한 논의로 채워진 것을 알 수 있다. 정책결정자들은 특히 허리케인 피해에 따른 정부와 민간의 지출 노력과 높은 에너지 물가가 인플레이션 우려를 강화시키고 있다고 봤다.의사록은 에너지 물가 급등은 "전반적인 인플레이션율을 상승시키며,일부는 코어 물가지수의 상승으로 이전될 것"으로 전망됐다. 또 이는 "인플레이션 압력의 지속에 따라 인플레이션 기대수준의 상승세를 자극하게 될 것"이라는 점에서 우려된다고 한다.한편 "실제로 최근 서베이에 따르면 이러한 인플레 기대가 상승하고 있으며, 재정적자 확대가 이러한 우려를 자극하는 요소로 지적되고 있다"고 의사록을 쓰고 있다.美 9월 연방공개시장위원회(FOMC) 의사록 전문(Minutes of the Federal Open Market Committee )September 20, 2005 A meeting of the Federal Open Market Committee was held in the offices of the Board of Governors of the Federal Reserve System in Washington, D.C., on Tuesday, September 20, 2005 at 9:00 a.m. Present: Mr. Greenspan, Chairman; Mr. Geithner, Vice Chairman; Ms. Bies; Mr. Ferguson; Mr. Fisher; Mr. Kohn; Mr. Moskow; Mr. Olson; Mr. Santomero; Mr. Stern ; Messrs. Guynn and Lacker, Mses. Pianalto and Yellen, Alternate Members of the Federal Open Market CommitteeMr. Hoenig, Ms. Minehan, and Mr. Poole, Presidents of the Federal Reserve Banks of Kansas City, Boston, and St. Louis, respectively--------------------------------------------------------------------------------The Manager of the System Open Market Account reported on recent developments in foreign exchange markets. There were no open market operations in foreign currencies for the System's account in the period since the previous meeting. The Manager also reported on developments in domestic financial markets and on System open market transactions in government securities and federal agency obligations during the period since the previous meeting. By unanimous vote, the Committee ratified these transactions. The information reviewed at this meeting suggested that, before the landfall of Hurricane Katrina on the Gulf Coast, expansion of economic activity had been solid, led by robust gains in housing and buoyant consumer spending. While business investment appeared to be losing some momentum, labor markets continued to improve, and increases in core CPI and PCE prices were modest after notable increases earlier in the year. Only limited data bearing on the likely economic effects of the hurricane were available. Oil and gasoline prices, however, were on the rise, spiking to record levels in the days immediately following the hurricane. Payroll employment grew at a good pace in August, and the average increase over the most recent three months was largely on par with the advances made since the fourth quarter of last year. Employment gains were widespread across industries, with the exception of the manufacturing sector, which continued to post small job losses. With employment increasing and the average workweek of production or nonsupervisory workers unchanged in August, aggregate hours continued to firm modestly. The unemployment rate dipped to 4.9 percent in August, its lowest level since August 2001. Given the increase in the labor-force participation rate reported for the month, the employment-population ratio rose to its highest level in three years. Initial claims for unemployment insurance jumped in the latest available week, however, as workers in the Gulf Coast region began to file claims. Industrial production increased only slightly in August; the staff estimated that the curtailment of activity as a result of Hurricane Katrina shaved 0.3 percent from the index. Petroleum refining and crude oil and natural gas extraction were especially hard hit by the storm. The output of utilities declined in August after surging earlier in the summer in response to unseasonably warm weather. Higher production of motor vehicles and parts boosted manufacturing output. After slowing in the second quarter, the pace of production in the high-tech sector accelerated somewhat in recent months, owing to increased output of communications equipment and semiconductors. Overall capacity utilization through August remained close to its highest level since December 2000. Real personal consumption expenditures, boosted by motor vehicles purchases in response to employee-discount programs, were robust during the summer. Spending on goods outside the automobile sector and on services was moderate. Strong overall spending along with lackluster real income growth put downward pressure on the saving rate. Survey measures of consumer confidence early in August were generally consistent with solid increases in spending, but confidence fell appreciably in the period immediately after the storm. Activity in the housing sector remained brisk. Starts of new single-family homes in July were slightly above their average level for the first half of the year. New home sales advanced further in July, and existing home sales stayed elevated. Mortgage rates remained low and supported demand. Prices of existing homes again rose briskly, while price appreciation for new homes moderated somewhat. Although real outlays for equipment and software increased solidly in the second quarter, available data on orders and shipments suggested some softness in the third quarter. Amid continued rapid expansion in business output, favorable financing conditions, and ample cash balances, the fundamentals stayed positive. Real spending on nonresidential construction remained lackluster despite incremental improvements in nonresidential property market conditions this year. Investment in real nonfarm inventories excluding motor vehicles slowed markedly in the second quarter, and partial data for July suggested that real stockbuilding continued to be subdued. The slower rate of inventory accumulation suggested that firms had largely completed the stockbuilding that had been prompted by earlier low ratios of inventories to sales. The U.S. international trade deficit narrowed somewhat in July, as the value of exports of goods and services rose slightly and the value of imports declined. The value of oil imports increased strongly in July but that rise was offset by decreases in imports of services and of non-oil goods. GDP growth in foreign industrial economies picked up, on balance, in the second quarter, but performance across economies was mixed. Core consumer price inflation remained benign in July and August. However, the surge in energy prices considerably boosted overall consumer price inflation over those months. Gasoline prices in particular rose steeply in August, and survey data pointed to a larger increase in early September. Producer price inflation was subdued. One survey of households in early September indicated that near-term inflation expectations jumped and that longer-term inflation expectations edged higher. With regard to labor costs, the employment cost index for private industry workers rose at a modest pace in the second quarter, and the twelve-month change in this index declined from that of a year earlier. Average hourly earnings rose only moderately over the past twelve months. At its August meeting, the Federal Open Market Committee decided to increase the target level of the federal funds rate 25 basis points, to 3-1/2 percent. In its accompanying statement, the Committee indicated that, with appropriate monetary policy action, the upside and downside risks to the attainment of sustainable growth and price stability should be kept roughly equal. In addition, the Committee noted that, despite high energy prices, aggregate spending appeared to have strengthened, labor market conditions continued to improve gradually, and longer-term inflation expectations remained well contained, although pressures on inflation had stayed elevated. In these circumstances, the Committee believed that policy accommodation could be removed at a pace that would likely be measured but noted that it would respond to changes in economic prospects as needed to fulfill its obligation to maintain price stability. The Committee's decision at its August meeting was widely expected in financial markets and evoked little price reaction. Over the intermeeting period, however, investors marked down their expectations for the path of policy, partly in response to the devastation caused by Hurricane Katrina. Nominal Treasury yields decreased about in line with the revision to policy expectations. Yields on inflation-indexed Treasury securities fell a bit more than their nominal counterparts, leaving inflation compensation slightly higher. Spreads on investment-grade corporate bonds were little changed over the intermeeting period, but those on speculative-grade bonds increased from very low levels. Major equity indexes appeared to be supported by lower interest rates and posted modest gains despite the increases in energy prices. The trade-weighted foreign exchange value of the dollar depreciated slightly over the intermeeting period. M2 grew moderately, on balance, in August. Liquid deposits edged higher, but retail money market mutual funds contracted, on net. Small time deposits, whose rates of return adjust relatively quickly to changes in market rates, continued to expand rapidly. The growth of bank credit surged, as loans expanded briskly. In the forecast prepared for this meeting, the staff lowered its projection for economic growth over the remainder of 2005 in light of the economic dislocation associated with Hurricane Katrina. At the same time, however, the staff increased the growth rate forecast for 2006 to reflect the boost to economic activity from the rebuilding effort. By 2007, the level of output was expected to move back to the path it would have followed in the absence of the storm. The staff revised upward its forecast of overall inflation for 2005 and of core inflation for 2006, reflecting the effects of higher energy prices, but lowered its projection for overall inflation slightly for 2006. It was recognized that there were considerable near-term uncertainties and that many data series in coming months would be influenced by the effects of the storm. In their discussion of the economic situation and outlook, meeting participants agreed that output and employment appeared to have been growing at a good pace before Hurricane Katrina's landfall. Business fixed investment had been a little softer than expected, but household spending had been especially strong. Participants agreed that the widespread devastation in the Gulf Coast region and the dislocation of many people would hold down indicators of spending for a time. But they also were of the view that aggregate demand and output would likely rebound before long, fueled in part by private spending to rebuild and outlays by the federal government to assist in the recovery. With growth of the economy expected to recover, meeting participants were concerned that price pressures, which had been elevated before the storm, could climb further, primarily as a result of additional increases in energy prices. Meeting participants recognized that Hurricane Katrina would have significant effects on the U.S. economy, but the size and timing of those effects were uncertain. Economic activity in the Gulf Coast region would be disrupted by the destruction of capital and the displacement of a large population, perhaps for an extended period. Moreover, damage to infrastructure for extracting and processing oil and natural gas was expected to be substantial, with significant near-term implications for energy prices and the national economy, and the projected track of Hurricane Rita raised additional concerns. In that environment, the prices of crude oil, natural gas, and gasoline likely would remain elevated and subject to considerable volatility, particularly given the limited spare capacity available in energy extraction and refining industries. Participants noted that very substantial rebuilding would probably be underway soon, supported importantly by government programs. The pace at which reconstruction activity would take place, however, was uncertain, as it depended in part on factors that were still difficult to assess, such as how quickly the affected areas could again be made habitable. On balance, participants thought that there would likely be a significant shift in the timing of aggregate economic activity over the next several quarters but probably little effect on the economy's intermediate-term growth prospects. Several participants voiced concern that the effects of the hurricane were likely to add to already considerable pressures on prices. For the nation as a whole, participants noted that household spending had been fairly robust before the hurricane, supported by strong advances in income and continuing gains in wealth that reflected in part further large increases in home prices. Most anecdotal information supported the indications from available data that activity in housing markets generally remained brisk. The termination of some inducements to purchase motor vehicles was expected to retard expenditures on consumer durables in the latter part of this year. The reduction in real disposable incomes caused by large increases in consumer energy prices was also anticipated to restrain consumer spending, with business contacts indicating that retail outlets that typically serve lower- and middle-income households could see particular weakness. The reduction in spending as a result of higher energy prices and hurricane-related dislocations could be augmented by a weakening of consumer attitudes. Many of the restraining effects were thought likely to dissipate over time, however. Retail energy prices were likely to retrace at least a portion of the post-hurricane increase, and consumer confidence should rebound. Moreover, demands for consumer durables, as well as housing, would receive support as hurricane victims repaired or replaced lost property, with help from insurance payments and government transfers. Although uncertainties about the outlook for spending had increased, it appeared that, over time, consumption would probably expand at a moderate pace--perhaps a little below the pace of income growth once the increases in house prices slowed to more historically typical rates. Meeting participants noted that, even prior to the hurricane, business fixed investment had been somewhat weaker than expected. The softness was somewhat puzzling, as sales were growing, business balance sheets appeared quite strong in the aggregate, profitability was high, and financing was readily available and relatively inexpensive for most firms. Although the apparent sluggishness could reflect only short-term fluctuations in volatile data series, some evidence suggested that it may also have stemmed from concern among business executives about the effects of high energy prices. The anecdotal information on commercial real estate markets was mixed, with some districts reporting firming markets while activity elsewhere was said to remain subpar. With regard to fiscal policy, meeting participants noted that federal outlays would increase sharply in order to assist with recovery and reconstruction efforts in the aftermath of the hurricane. The eventual size of the increment to federal outlays was unclear, but it was likely to be quite large. The substantial step-up in government spending would add to federal deficits that were already large and underscored the worrisome loss of fiscal discipline evident in recent years. The expansion of federal spending implied an increase in fiscal stimulus at a time when the margin of unutilized resources in the overall economy was probably thin. Participants' concerns about inflation prospects generally had increased over the intermeeting period. The surge in energy prices, in particular, was boosting overall inflation, and some of that increase would probably pass through for a time into core prices. This posed the risk that there could be a more persistent influence on inflation should inflation expectations rise. Indeed, some recent survey evidence on such expectations had been troubling, and widening federal deficits were mentioned as a factor that could further stir inflationary concerns. Measures of labor costs were giving conflicting signals, with some indexes indicating that growth in labor compensation remained relatively low but another showing appreciably more rapid increases. Anecdotal information continued to point to shortages of certain types of labor, such as truck drivers, and some business contacts reported difficulties in hiring more generally, a development that had prompted some firms to boost wages. Underlying productivity growth to date apparently had remained robust but, at this stage of the business cycle, gains in productivity could not necessarily be counted on to stay strong. The prices of a number of intermediate goods, including a wide range of petrochemical products and building materials, were subject to upward pressure, reflecting high crude oil prices, production disruptions in the energy sector, and elevated demands for materials in anticipation of rebuilding in the Gulf Coast region. Still, core inflation in recent months had been quite damped, and market-based measures of longer-term inflation expectations had risen only modestly of late. It was observed that, after the early 1980s, the pass-through of energy prices into core inflation had been quite limited, suggesting that, in current circumstances, core inflation could stay relatively low and overall inflation would probably drop back if inflation expectations remained contained. In the Committee's discussion of monetary policy for the intermeeting period, nearly all members favored raising the target federal funds rate 25 basis points to 3-3/4 percent at this meeting. Although uncertainty had increased, in the Committee's judgment the fundamental factors influencing the longer-term path of the economy probably had not been affected by the hurricane, but the upside risks to inflation appeared to have increased. Even after today's action, the federal funds rate would likely be below the level that would be necessary to contain inflationary pressures, and further rate increases probably would be required. Moreover, the uncertainties about near-term economic prospects resulting from Hurricane Katrina would probably not be reduced materially in coming weeks. Indeed, underlying economic trends would be particularly difficult to assess over the next several months as a result of the direct, and presumably temporary, effects of the storm and its aftermath on the incoming data. A pause in policy tightening at this meeting had the potential to mislead the public both about the Committee's perceptions of the fundamental strength and resilience of the economy and about its commitment to fostering price stability. In discussing the statement to be released after the meeting, members agreed that it would be appropriate to characterize the macroeconomic effects of Hurricane Katrina, while significant, as essentially temporary. Members also believed that the statement should again note that both monetary policy accommodation and robust underlying productivity growth were continuing to support economic activity. Although energy prices had the potential to add to inflation pressures, and inflation expectations had recently exhibited some signs of increasing, members agreed that the risks to inflation, as well as those to growth, remained essentially balanced under an assumption of appropriate policy action. The Committee also agreed to reiterate its previous expectation that ". . . policy accommodation can be removed at a pace that is likely to be measured." However, some sentiment was expressed to consider changes to forward-looking aspects of the statement at upcoming meetings, in part because of the considerable reduction in monetary policy accommodation that had already been accomplished. At the conclusion of the discussion, the Committee voted to authorize and direct the Federal Reserve Bank of New York, until it was instructed otherwise, to execute transactions in the System Account in accordance with the following domestic policy directive: "The Federal Open Market Committee seeks monetary and financial conditions that will foster price stability and promote sustainable growth in output. To further its long-run objectives, the Committee in the immediate future seeks conditions in reserve markets consistent with increasing the federal funds rate to an average of around 3-3/4 percent."The vote encompassed approval of the paragraph below for inclusion in the statement to be released shortly after the meeting: "The Committee perceives that, with appropriate monetary policy action, the upside and downside risks to the attainment of both sustainable growth and price stability should be kept roughly equal. With underlying inflation expected to be contained, the Committee believes that policy accommodation can be removed at a pace that is likely to be measured. Nonetheless, the Committee will respond to changes in economic prospects as needed to fulfill its obligation to maintain price stability." Votes for this action: Messrs. Greenspan and Geithner, Ms. Bies, Messrs. Ferguson, Fisher, Kohn, Moskow, Santomero, and Stern. Vote against this action: Mr. Olson.Mr. Olson dissented because he preferred that the Committee defer policy action at this meeting, pending the receipt of additional information on the economic effects resulting from the severe shock of Hurricane Katrina. It was agreed that the next meeting of the Committee would be held on Tuesday, November 1, 2005. The meeting adjourned at 1:15 p.m. Notation VoteBy notation vote completed on August 29, 2005, the Committee unanimously approved the minutes of the meeting of the Federal Open Market Committee held on August 9, 2005. Vincent R. ReinhartSecretary Footnote 1. Attended Wednesday's portion of the meeting.2. Attended Thursday's portion of the meeting. [뉴스핌 Newspim] 김사헌 기자 herra79@newspim.com

[관련키워드]


[뉴스핌 베스트 기사]
 사진
李대통령, 시정연설서 '성장' 36차례 강조
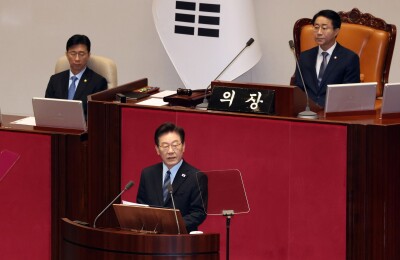
[서울=뉴스핌] 박찬제 기자 = 이재명 대통령은 2일 국회에 2027년도 예산을 '성장 확산 예산'이라고 설명하며 적극적인 협조를 요청했다. 이 대통령은 특히 '성장'이라는 단어를 가장 전면에 내세우며 '투자' '국민' '지원' '미래'를 함께 강조했다.
이 대통령은 이날 오전 2027년도 예산안 국회 시정연설을 통해 820조 9000억 원 규모의 예산안 주요 사용처를 국회에 설명했다.
이 대통령이 가장 많이 언급한 단어는 '성장'으로 연설 중 36차례 등장했다. 이어 '투자' 24차례, '국민' '지원'이 각각 22차례, '미래'가 16차례 언급됐다.
[서울=뉴스핌] 국회사진기자단 = 이재명 대통령이 2일 오전 서울 여의도 국회에서 열린 제439회 국회(정기회) 제11차 본회의에서 2027년도 예산안 및 기금운용계획안에 대한 시정연설을 하고 있다. 2026.11.02 photo@newspim.com
◆"연간 수출 1조 달러 가시권"
이 대통령은 먼저 "우리 경제는 뚜렷한 V자형 회복세를 이어가고 있다"며 "40여 년 만에 잠재성장률이 2년 연속 반등할 것이라는 전망이 나오고 올해 상반기에만 3.8% 성장률을 기록했다"고 소개했다.
이 대통령은 "반도체를 비롯한 주력산업의 활약으로 연간 수출 1조 달러(1341조원) 달성이 가시권에 들어왔다"고 국가 경제의 성장세를 설명했다.
이어 "1인당 국민총소득도 4만 달러(5400만원)를 넘으며 인구 5000만 명 이상 국가 중에 세계 6번째로 '5040 클럽'에 진입할 것으로 전망된다"고 했다.
이 대통령은 "1998년 외환위기 때 투입한 공적자금도 내년이면 모두 상환하게 된다"며 "2003년부터 25년에 걸쳐 97조2000억 원을 갚아 30년 만에 국제통화기금(IMF) 위기 극복을 완벽하게 졸업하게 된다"고 강조했다.
다만 국가 경제의 전체적인 성장세 이면에 '양극화의 그늘'이 있다고 지적했다.
이 대통령은 "이러한 성과에도 불구하고 우리 사회에는 여전히 불평등과 양극화의 그늘이 짙게 드리워져 있다"며 "청년에게 첫 일자리 문턱은 높기만 하고 소상공인의 시름은 깊고 지역경제의 회복도 참으로 더디다"고 짚었다.
양극화 해법으로 이 대통령은 "특정 지역과 계층, 소수 기업에 성장의 기회와 성과가 집중되는 '소수의 성장'이 아니라 모든 지역과 모든 국민이 성장의 기회와 성과를 고르게 누리는 '모두의 성장'으로 대전환해야 한다"고 강조했다.
재정을 통한 투자도 강조했다. 이 대통령은 "국민적 노력으로 확보한 추가세수를 청년과 미래 성장동력, 지방, 교육·인재라는 4개의 축에 집중 투자함으로써 우리 사회의 깊은 격차를 완화함과 동시에 이를 기반으로 성장 발전의 토대를 탄탄하게 구축하게 될 것"이라고 기대했다.
내년 예산안의 중요 원칙 중 하나로 이 대통령은 "담대하게 투자하되 비효율에 낭비하지 않는다"라고 강조했다. 이 대통령은 "국토대전환과 지방주도성장에 올해의 2배가 넘는 33조 원을 투자한다"고 언급했다.
이 대통령은 "대한민국 미래를 위한 투자를 확대하겠다"며 "한국 경제의 기초체력인 성장 잠재력을 끌어올리기 위해 인공지능(AI)과 미래 성장동력에 과감히 투자하겠다"고 역설했다.
이 대통령은 "3대 메가프로젝트인 반도체와 피지컬 AI, AI 데이터센터와 AI 투자에 올해보다 2배 가까이 늘어난 21조3000억 원을 투자하겠다"고 약속했다.
[서울=뉴스핌] 국회사진기자단 = 이재명 대통령이 2일 오전 서울 여의도 국회에서 열린 제439회 국회(정기회) 제11차 본회의에서 2027년도 예산안 및 기금운용계획안에 대한 정부의 시정연설을 하는 가운데 함께 참석한 국무위원들이 자리하고 있다. 2026.11.02 photo@newspim.com
◆'지방' 15차례, '재정' 13차례, '경제' '국회' '예산' 각 12차례 언급
이 대통령은 '지방' 15차례, '재정' 13차례, '경제' '국회' '예산'을 12차례씩 언급했다.
지방과 관련해 이 대통령은 "국토균형발전과 지방소멸방지를 위해 수도권에서 멀어질수록 더 두텁게 지원하는 지방우대 사업도 61개로 대폭 늘렸다"고 소개했다급했다.
국가 재정과 관련해 이 대통령은 "국내총생산(GDP) 대비 관리재정수지는 올해 –3.9%였는데 내년에는 –0.1%로 20년 만에 가장 양호해진다"며 "이에 따라 GDP 대비 국가채무 비율도 51.6%에서 48.3%로 낮아지게 된다"고 설명했다.
특히 이 대통령은 "국채를 발행하기는 하지만 거의 대부분을 기존 국채 상환에 사용해 국채의 순증가분이 거의 없다"고 강조했다.
국회에 초당적 협력을 요청했다. 이 대통령은 "국가의 미래와 국민의 삶을 위해 정부와 국회가, 여와 야가 모두 함께 힘을 모아야 될 때"라며 "내년도 예산안과 부수 법안이 법정 기한인 12월 2일까지 확정될 수 있도록 국회의 적극적인 협력을 부탁드린다"고 했다.
이 대통령은 "정부는 심의 과정에서 여와 야를 가리지 않고 제기되는 의견에 대해서 열린 마음으로 경청하고 더 나은 대안을 적극 반영하겠다"며 "위대한 대한국민을 믿고 국회와 적극 소통하며 새로운 대한민국 미래를 힘있게 열어가겠다"고 힘줘 말했다.
pcjay@newspim.com
2026-11-02 14:45
 사진
KT 대니엘 vs 삼성 최원태...KS 1차전 선발
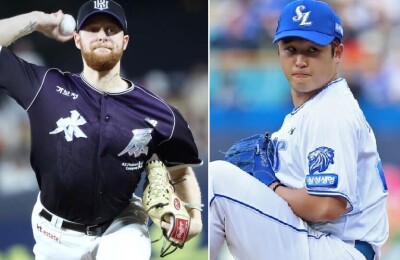
[서울=뉴스핌] 박상욱 기자 = KT 위즈가 삼성 라이온즈와 한 번도 맞붙지 않았던 외국인 투수 데이비스 대니엘을 한국시리즈 1차전 선발로 내세운다. 삼성은 플레이오프에서 부진했던 최원태에게 다시 기대를 건다. 정규시즌 1위 KT와 플레이오프를 거쳐 올라온 삼성의 첫 승부는 선발 투수의 컨디션과 상대 타선의 적응력이 핵심 변수가 될 전망이다.
이강철 KT 감독과 박진만 삼성 감독은 2일 수원 라마다프라자 호텔에서 열린 2026 신한 SOL KBO 한국시리즈 미디어데이에서 1차전 선발 투수를 발표했다. 대니엘과 최원태는 3일 오후 6시 30분 수원케이티위즈파크에서 열리는 한국시리즈 첫 경기에 나선다. 한국시리즈는 7전 4선승제로 진행된다.
KT는 정규시즌 1위에 오른 뒤 선발진 가운데 대니엘을 일찌감치 낙점했다. 공동 다승왕 고영표와 좌완 로건 앨런도 후보였지만 이 감독의 선택은 대니엘이었다. 시즌 중반 대체 외국인 선수로 합류한 대니엘은 짧은 기간 에이스로 자리 잡았다.
[서울=뉴스핌] 박상욱 기자 = 데이비스 대니엘(왼쪽)과 최원태. [사진=KT 위즈, 삼성 라이온즈] 2026.11.02 psoq1337@newspim.com
대니엘은 올해 7월 30일 맷 사우어의 대체 선수로 KT에 합류했다. 정규시즌 10경기에서 5승 2패 평균자책점 2.13을 기록했다. 9월 이후에는 7경기에서 5승 1패 평균자책점 1.85로 더 강한 모습을 보였다. 수원 홈에서는 5경기 평균자책점 1.16을 기록했다.
삼성 타자들이 대니엘의 공을 경험하지 못했다는 점도 KT가 기대하는 대목이다. 대니엘은 정규시즌 삼성전에 한 차례도 등판하지 않았다. 이 감독은 시즌 막판 삼성전에 투입해 점검하는 방안도 검토했지만 상대에게 공을 보여주지 않는 편이 낫다고 판단했다.
이 감독은 "정규시즌 막판 삼성전에 투입해 테스트해볼까 고민했으나 아예 안 보여주는 것이 낫다고 생각했다"며 "일찌감치 대니엘을 1차전 선발로 결정했다"고 말했다. 이어 "2021년 한국시리즈 우승 때도 확실한 1선발이 없었다. 시즌을 치르면서 1선발이 완성됐다. 대니엘도 경기를 통해 1선발로 맞춰간 것 같다"고 설명했다.
[서울=뉴스핌] 박상욱 기자 = KT 이강철 감독. [사진=KT 위즈] 2026.11.02 psoq1337@newspim.com
다만 대니엘의 실전 감각은 변수다. 마지막 정규시즌 등판은 지난달 6일 키움전이었다. 약 한 달 동안 공식 경기에 나서지 않았다. 충분한 휴식이 구위 회복으로 이어질 수 있지만, 경기 초반 감각을 얼마나 빠르게 끌어올리느냐가 관건이다.
삼성은 선발 선택의 폭이 넓지 않았다. 크리스 페덱과 아리엘 후라도가 플레이오프 4·5차전에 잇따라 선발 등판했다. 원태인도 불펜으로 이동해 5차전까지 마운드에 올랐다. 순번상 최원태가 한국시리즈 1차전을 맡게 됐다.
최원태는 정규시즌 24경기에서 7승 5패 평균자책점 4.68을 기록했다. KT를 상대로는 두 차례 등판해 1패 평균자책점 6.94에 그쳤다. 두 경기 모두 수원에서 열렸다. 4월 4일에는 5이닝 5실점, 6월 9일에는 6⅔이닝 4실점을 기록했다. KT 타선에 약점을 드러냈던 만큼 이번 등판은 설욕의 기회다.
플레이오프에서의 부진도 부담이다. 최원태는 지난달 29일 KIA와 플레이오프 3차전에 선발 등판해 1.2이닝 동안 3피안타 1볼넷 2실점하고 조기 강판했다. 투구 수는 38개였다. 짧은 이닝에 그친 만큼 체력 부담은 크지 않다. 다만 한국시리즈 첫 경기에서 제구와 경기 운영을 회복해야 한다.
[서울=뉴스핌] 삼성의 박진만 감독이 1일 열린 PO 5차전에서 승리한 후 인터뷰를 하고 있다. [사진 = 삼성 라이온즈] 2026.11.01 wcn05002@newspim.com
박진만 감독은 최원태의 경험에 기대를 걸었다. 그는 "원태인이 불펜으로 들어가면서 순번상 최원태가 선발로 나선다"며 "플레이오프에서 다소 부진했으나 경험이 많다. 지난해 가을야구에서 활약했던 모습을 다시 펼쳤으면 한다"고 말했다.
KT 타선에서는 김현수가 최원태의 경계 대상이다. 김현수는 최근 두 시즌 최원태를 상대로 10타수 5안타 5타점을 기록했다. 안현민과 류현인도 최원태를 상대로 안타를 때려낸 경험이 있다. 최원태가 초반 제구를 잡지 못하면 KT 타선이 빠르게 승부를 흔들 가능성이 있다.
두 팀은 한국시리즈 우승을 향한 목표도 뚜렷하다. KT는 2021년 이후 5년 만의 통합 우승을 노린다. 삼성은 2014년 이후 12년 만에 한국시리즈 정상에 도전한다. 역대 한국시리즈에서 1차전 승리 팀은 42차례 가운데 31차례 우승했다. 우승 확률은 73.8%다.
psoq1337@newspim.com
2026-11-02 15:36